Striped commercial lawn with clipped hedging alongside

Lawn care and landscaping insurance

Landscaping insurance usually combines general liability for property damage and injury, workers compensation for crews, commercial auto for trucks and trailers, and equipment cover for mowers and machinery. Herbicide and tree-felling work usually needs specific endorsement.

Talk to an expert

Get a quote

Core coverage

What landscaping insurance covers

Two lines carry the weight, and on a grounds book they pull in opposite directions: one follows the crew, the other follows the kit.

01Carries the weight

Workers compensation. A crew that is not the same size twice in one year.

Medical costs and lost wages when a groundworker is hurt. Frequency lives with blades, strains and heat; severity lives with chainsaws, chippers and anything done above ground level. Premium is built on payroll, so a seasonal crew makes this the line that moves most.
02Carries the weight

General liability. Other people's property.

Third-party injury and property damage arising from your work. A stone thrown by a mower deck through a window, a client who trips on a hose, and, where chemical application has been endorsed, a neighbour's hedge that dies after spray drifts onto it.

03Fills a gap

Equipment and inland marine

Mowers, blowers, chippers, aerators, hand tools. This is usually the largest asset a grounds business owns and the most exposed, because it sleeps outdoors more nights than it sleeps inside.

04Fills a gap

Trailers, owned and hired

The trailer itself is a vehicle question, and what is strapped to it is an equipment question. Usually two different policies, and a gap between them that people find at the worst moment.

05Fills a gap

Commercial auto

Trucks, plus hired and non-owned auto for a crew member running to the yard in their own car. Towing changes the rating, so say what you tow and how heavy it is.

06Fills a gap

Herbicide and pesticide endorsement

Chemical application is treated separately from mowing, and the standard pollution exclusion generally reaches it unless it is added back. If you spray, this is not optional.

07Fills a gap

Commercial property or a BOP

The yard, the shop, the fuel and the stock. Bundled into a business owner's policy for smaller operations.

Equipment is the schedule that dates fastest on this trade, because machines get replaced mid-season and rarely get added to anything. Our brokers can review mowers, blowers and trailers against a current list rather than last spring's, and look at whether bundling the yard and the shop is the cheaper way to hold the rest.

Your operation

Four grounds businesses, four different policies

Most grounds companies do several of these, and the mix often moves the rate more than the size of the business does. Pick the closest match to your revenue.

Residential lawn care

Route work, high volume, small tickets. The exposure is not the mowing, it is the two hundred properties a week where something can be thrown, scratched, sprayed or left open.

What underwriters askProperty count per week, crew size at peak, and whether you apply any chemicals at all
The claim that shows upThrown-object damage to glass and vehicles, damage to irrigation heads, turf killed by an application
Endorsements it needsHerbicide and pesticide endorsement, care custody and control, hired and non-owned auto
Watch forA mower deck throws stone at speed. Windows and parked cars are among the most common general liability claims on a route book.Talk to a broker about this

If you added tree work or chemical application since your last renewal and have not told anyone, that is worth a call before the next storm rather than after it.

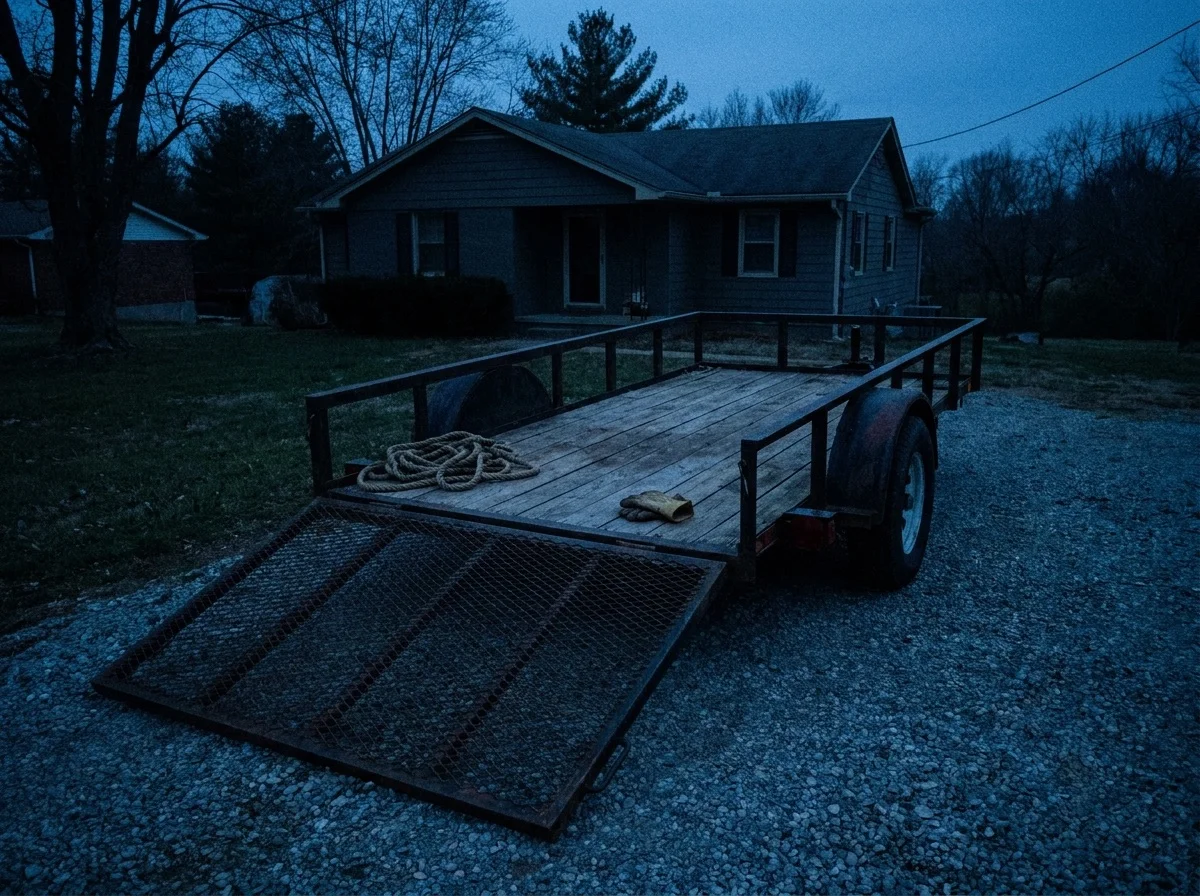
Empty landscaping trailer with its ramp down on a driveway at dusk

What actually leaves the yard

Ask a grounds business what its biggest loss was and you rarely hear about a lawsuit. You hear about a trailer. Equipment on this trade is high value, highly portable and stored outdoors, and on many grounds books it is the loss that happens most, costs most in downtime, and is most often underinsured.

Where the cover sits, and where it does not:

Typically covered: Machines taken from a locked trailer or a secured yard, where the schedule lists them and the limit is current.

Typically not covered: The mower you bought in June and never added. Scheduled equipment cover pays against the list, and once any newly acquired equipment period runs out an unlisted machine is generally an uninsured one.

Typically covered: The trailer itself, if it carries physical damage cover on the auto policy or is scheduled on the equipment floater.

Typically not covered: Anything taken from an unsecured, unattended trailer where the wording requires forced entry. Read that clause before you need it.

The second loss is the crew. Payroll drives comp, and a business that runs six people in winter and eighteen in July is quoted on an estimate and settled on the truth. That gap is the subject of the premium audit section below. Worth understanding how a class code gets assigned before the estimate is set, because the code does more work than the number does.

The gaps

What landscaping insurance does not cover

Eight that matter on a grounds schedule. Several of them are the difference between a policy that answers in August and one that does not.

Herbicide and pesticide drift

WHAT YOU NEED

A chemical application endorsement. Most wordings exclude application damage under the pollution exclusion unless it has been declared and added back, and the usual add-back applies only where the work meets the licence and regulatory rules that govern it.

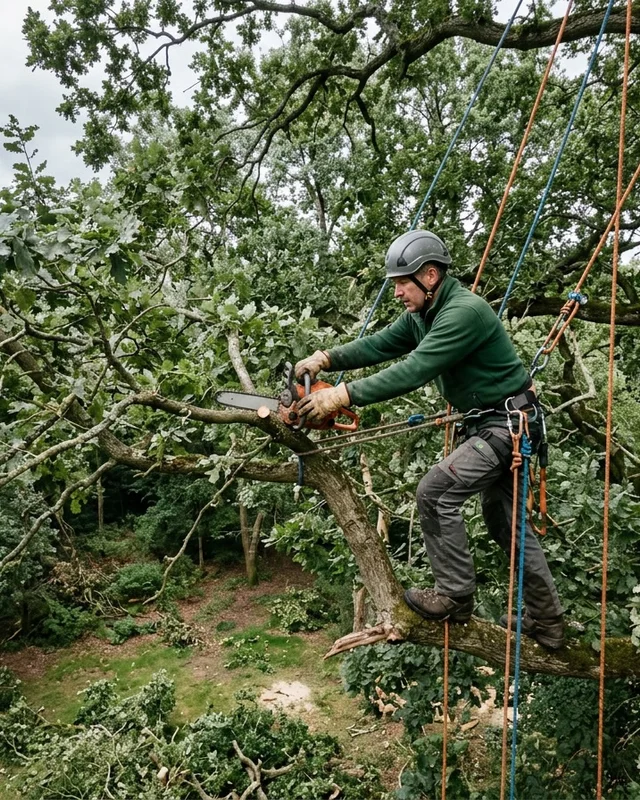
Tree felling above a stated height

WHAT YOU NEED

Tree work declared and rated. Some carriers cap the height, some decline it, and none of them should be relied on to cover it by accident.

Equipment from an unsecured trailer

WHAT YOU NEED

Equipment cover whose unattended-vehicle clause you have actually read. Forced entry is a common condition and an open trailer rarely satisfies it.

Machines not on the schedule

WHAT YOU NEED

A current equipment list. On a scheduled form cover follows the schedule, so a machine bought mid-season and never added may not be insured at all once any newly acquired equipment period has run out.

Damage to buried services

WHAT YOU NEED

An underground strike buy-back if you dig for irrigation, footings or drainage. Excluded on many contractor wordings.

Employee injury

WHAT YOU NEED

Workers compensation. General liability answers for third parties, and a seasonal hire is still your employee.

Anything involving a vehicle or trailer

WHAT YOU NEED

Commercial auto with the trailer declared, plus hired and non-owned. General liability stops at the tow hitch.

Plants that do not take

WHAT YOU NEED

Nothing, generally. Replacing your own failed work is a cost of doing business, not a claim. Price replacement into the contract.

The first two are the ones that quietly decide whether you have a policy at all in a bad month, because both are often excluded by default rather than by exception. Speak to our team before you take on spraying or felling, and ask about cover for a seasonal crew at the same time.

The premium audit

What the audit finds after the season

Comp and liability are usually quoted on an estimate at the start of the year and settled on what actually happened at the end of it. On a seasonal trade that gap is wider than almost anywhere else, and it is a common unpleasant surprise.

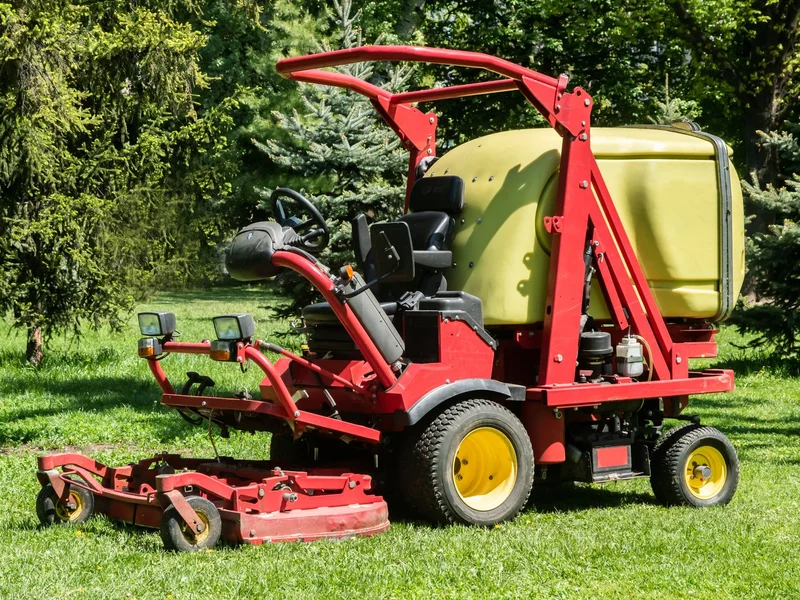
Ride-on mower and grounds equipment parked on a maintained lawn

You are quoted on a number you guess in January

Premium is built on projected payroll and projected revenue. In a business whose headcount doubles between March and July, that projection is an estimate made at the least representative moment of the year.

Rolls of turf loaded on a barrow beside a store of grounds tools

The auditor reconciles it against reality

At the end of the term the carrier compares the estimate to actual payroll and receipts. If the season ran hot, the adjustment usually lands as one invoice, after the cash from that season has already been spent.

Barrow of cuttings and hand tools left beside a clipped hedge

Classification is where it bites hardest

A crew member who mows is usually not in the same class as one who climbs, and an uninsured subcontractor's payroll is often charged to your policy at audit. Both are decided on paper you should keep during the season, not assemble afterwards.

None of this is avoidable, but all of it is predictable. A realistic estimate, honest class splits and certificates collected from every subcontractor turn the audit into an adjustment rather than an event. It is also where the modifier on later renewals starts being decided.

Speak to our team

Season check

What does your season actually include?

A grounds policy is quoted on a snapshot and lived in across twelve very different months. Most lines here change the wording, the rating or the audit. Nothing is priced and nothing is submitted.

What the schedule would have to carry

Nothing ticked yet. Choose what your season includes and the schedule it implies will build here.

Take this into the renewal conversation. Declaring work you already do costs a fraction of discovering it was never covered. This is general information about how these coverages usually work, not a determination about your policy: what responds depends on your wording and your carrier.

Speak to our team

Cost

How much does landscaping insurance cost?

No flat answer exists, and on a seasonal trade a published figure is even less useful than usual. Six inputs move a grounds premium more than the rest.

01

Peak payroll, not average payroll

Comp is built on payroll and the audit settles on the real number. A business that quotes on its winter crew and works with its summer crew is buying a bill it has not budgeted for.

Effect on premium
02

Whether you do tree work

Nothing else on this list changes the file as much. Climbing and felling can move the comp class, the liability appetite and the list of carriers who will quote at all.

Effect on premium
03

Chemical application

Whether you spray, what you spray and who holds the licence. It is rated separately from mowing because it fails differently.

Effect on premium
04

Equipment values and where it sleeps

The schedule total, and whether machines are yarded, garaged or left on a trailer. Storage can move this line more than the total does.

Effect on premium
05

Trucks, trailers and towing

Vehicle count, what you tow and how far you travel. Towing is rated, and an undeclared trailer is a claim waiting to be argued.

Effect on premium
06

Claims history and experience modifier

Three years of loss runs and the modifier they produce. On a high-frequency trade the modifier can climb faster than most owners expect.

Effect on premium

Three marks is an input that moves a grounds premium more than the others listed here. It is a relative weighting drawn from how these behave on a seasonal trade, not a rate and not a quote.

So what does that add up to?

Comp is the larger half on many grounds books, and it is largely decided by payroll and class before anyone considers your safety record. The half you can move is the accuracy of what you declare. Request a quote and we will take your real exposure to market.

Talk to an expert

Process

How a placement works

We understand your business first, then take it to the carriers who want to write it. An advisor walks you through what comes back and what it costs. No two files are the same, so what follows is the shape of a placement rather than a script.

  1. Loss runs and a payroll schedule spread on a desk beside a calculator and laptop

    We understand the business first

    What you do, where, with how many people, and what your contracts oblige you to carry. Those answers decide which markets will look at the file at all, and how much of the rest of this applies to you.

  2. Brokerage desk with a monitor in morning light

    We match it to the carriers who want to write it

    One set of information goes to underwriters we know have appetite for grounds work rather than whoever happened to quote last renewal. An advisor talks you through what comes back and what it costs.

  3. Stamped certificate on a clipboard with a pen and a magnifier

    After bind, certificate requests read against the contract

    A main contractor wants proof before your crew can start, and this is how COIs get issued here. We read the certificate request against your contract, so the endorsements the contract needs are requested on the policy and the certificate reports what the policy provides, rather than a generic endorsement that may fail review.

Not by federal statute, and licensing varies far more than it does for the building trades, though spraying for hire can require a state licence that requires liability insurance (Texas does). Otherwise what makes it compulsory in practice is the contract: property managers, HOAs and councils typically require proof of general liability before a crew sets foot on site. Workers compensation sits under a different rule: required in every state except Texas and South Dakota, where it is optional, and the employee count that triggers it varies by state.

The two answers that move it most are your peak payroll and whether you touch trees. Everything else, equipment values, truck count, spraying, loss history, adjusts around those. We would rather ask what your July looks like than publish a figure calculated on somebody's January.

Often yes, subject to your terms, with two conditions that catch people out. On a scheduled form the machine has to be on the schedule, so anything bought mid-season and not added may be uninsured once any newly acquired equipment period runs out, and the unattended-vehicle clause often requires forced entry, which an open trailer does not satisfy. Both are worth reading before a bad Monday morning.

Generally yes. The pollution exclusion in a standard general liability wording generally reaches herbicide and pesticide application, and it is added back by endorsement, usually only when the work has been declared and meets the licensing and regulatory rules that apply to it. If a proportion of your revenue is applications, that has to be on the submission rather than discovered at claim stage.

More than almost anything else you could add. Climbing and felling usually move the workers comp class, change the liability appetite and shorten the list of carriers willing to quote. Some exclude felling above a stated height outright. Tell your broker before the first job, not at renewal.

That is most likely the premium audit. Comp and liability are quoted on estimated payroll and revenue, then reconciled against actuals at the end of the term. On a seasonal business the estimate is often low, and the correction usually arrives as a single invoice once the season's cash has gone.

Not as subcontractors, and often worse than that. If a sub cannot produce a certificate, carriers often treat their payroll as yours at audit and charge you for it, and their injuries can land on your comp. Collect certificates before anyone starts, not after.

If you take it, yes, and it should be declared separately. Snow and ice operations carry a slip-and-fall exposure that behaves nothing like mowing, and a policy rated purely on grounds maintenance may not contemplate it at all.

Get started

Cover sized for July, not for January.

Tell us what your season actually looks like at its busiest, and we will go to market for terms built on that season rather than on your quietest month.

  • Contract insurance schedules read with you
  • Direct and wholesale carrier access
  • Markets that write grounds work

This page is general information, not a coverage determination. What your policy covers is governed by its own terms, conditions, and exclusions.

Aerial view of a manicured commercial landscape with clipped hedge lines