01The foundation
General liability. The room, and the people in it.
Third-party bodily injury, property damage and personal and advertising injury. A customer injured in the dining room, or damage you cause to a neighbouring tenant.
A customer claims they got food poisoning after your Saturday dinner service. A walk-in fails overnight and takes the week's stock with it. A fryer flares and the suppression system discharges over the line. No single form covers a restaurant completely, and the three losses above are the ones a standard package handles worst.
Talk to an expertGet a quote
The package
No single policy covers a restaurant. Coverage comes from several working together, each answering a different category of loss, and the value is in whether they line up at the seams.
Third-party bodily injury, property damage and personal and advertising injury. A customer injured in the dining room, or damage you cause to a neighbouring tenant.
The building if you own it, plus kitchen equipment, fit-out, furniture and stock. In a commercial kitchen the equipment value alone usually exceeds what the owner estimates.
Kitchen work is physically demanding, and burns, cuts and slips on wet floors are daily hazards rather than edge cases. The class code reflects that.
The cost of closing, deep cleaning, disposing of stock and reopening after a contamination event, which a standard property form does not answer at all.
Stock lost when a power outage or an equipment failure takes out refrigeration. A walk-in failing overnight is a whole-week loss, and it is endorsed rather than automatic.
Lost revenue and continuing costs while the kitchen is rebuilt. A commercial kitchen fire closes an operation for longer than owners expect, because the equipment queue outlasts the building work.
Where alcohol is a profit centre the package needs cover for serving alcohol as a separate policy rather than an assumption, and a kitchen fire usually needs cover for the income you lose while closed sized on the equipment queue rather than the building work.
Your operation
Coverage that works for a counter-service sandwich shop does not fit a full-service kitchen with a liquor licence. What changes most is the food handling: how much is prepared on site, how much is held, and how far it travels before somebody eats it.
High foot traffic, a full kitchen, alcohol service and a delivery side that most owners forget to declare on the submission.
Food trucks carry a version of all of this plus a vehicle. Commercial auto is required for the truck itself and the property policy has to cover a mobile kitchen, which most standard restaurant forms are not written for. Bars, taverns and nightlife venues are a different risk picture again, dominated by alcohol and the crowd rather than by the kitchen.
The package answers the ordinary accidents of a premises well enough. What it handles worst is the food itself: what happens to it, what it does to somebody, and what it costs when the cold chain breaks. Those three need endorsements that are frequently not there.
Four losses in one kitchen, and which of them the standard forms answer:
Covered: A customer is injured in the dining room. General liability, with defense included.
Not covered: Stock spoils when a walk-in fails overnight. That needs a spoilage endorsement, and the property form alone will not answer it.
Covered: A fire on the cooking line damages the kitchen and the fit-out. Property, plus business income if it has been endorsed.
Not covered: A health department closes the kitchen after a foodborne illness report. The cleaning, restocking and reopening need a food contamination endorsement.
The pattern is worth naming. The premises risks are handled by the standard forms without argument. The food risks are handled by endorsements that have to be asked for, and they are the three losses most likely to actually close a kitchen. Where a closure runs long, cover for the income you lose while closed is what carries the rent and the payroll through it.
The gaps
This is where most operators get caught. A standard general liability and property package leaves meaningful gaps, and the ones that matter most in food service are the ones nobody asks about until the claim. Eight that matter.
WHAT YOU NEED
A spoilage endorsement. The property form excludes breakdown and power failure, for the unit and for what was inside it.
WHAT YOU NEED
A food contamination endorsement. Product liability answers the claimant; this answers the closing, cleaning and reopening.
WHAT YOU NEED
Business interruption. The rebuild is only half of a kitchen fire and usually the shorter half.
WHAT YOU NEED
Dedicated liquor liability. Standard general liability excludes it whether you serve spirits, beer or wine.
WHAT YOU NEED
Workers compensation, which in a kitchen is anything but a formality.
WHAT YOU NEED
An A&B endorsement, frequently sub-limited. It matters most where alcohol and late hours dominate the room.
WHAT YOU NEED
Cyber liability. Card data and delivery platform integrations are both exposure.
WHAT YOU NEED
EPLI, and read the wage-and-hour exclusions carefully, because that is the claim food service actually gets.
The first three on that list are the food gaps and they are the three this page exists for. All three are endorsements rather than separate policies, which makes them cheap to add and easy to leave off. Where alcohol is part of the operation, cover for serving alcohol is the fourth, and it can be its own policy or an endorsement.
The kitchen
A restaurant's premises risks are well served by ordinary forms. A customer falls, a pipe bursts, a neighbour's ceiling gets wet, and general liability and property answer all of it without argument. The food is different. Three losses sit at the centre of a food business, and each one needs something that has to be asked for.
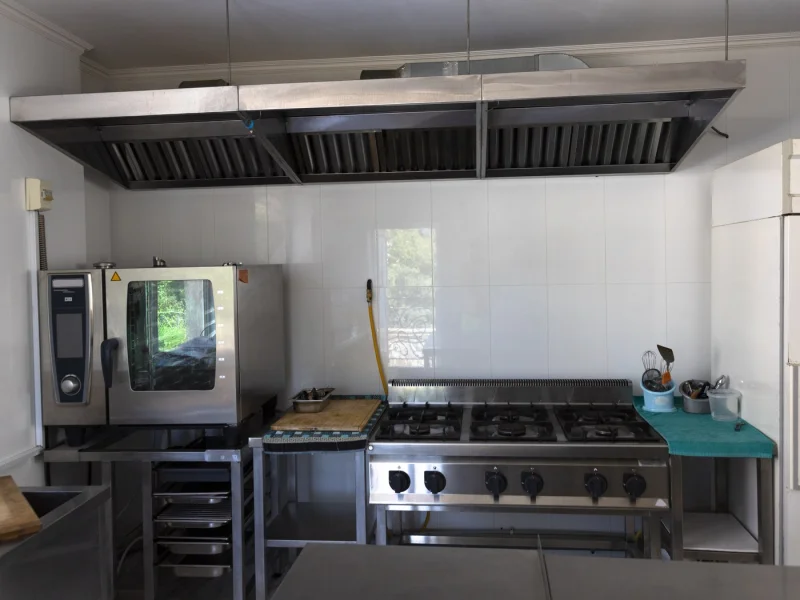
Commercial kitchen fires start at the range and travel through the grease in the flue. Carriers rate on the age of the suppression system and on the inspection record: newer systems with documented inspections lower property rates, and older wiring or non-compliant hoods raise them. This is the one input on the whole page you can improve before a renewal rather than after a loss.
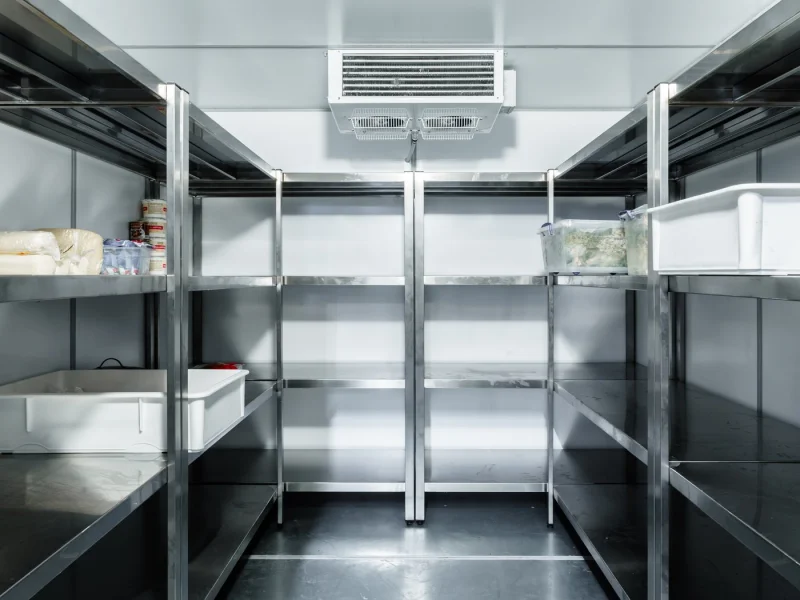
A walk-in failing overnight takes the week's stock with it, and the property form excludes breakdown and power failure, for the unit and the contents alike. Spoilage is an endorsement, sized to your cold storage rather than to your turnover, and it is the single most commonly missing item on a restaurant schedule.
A foodborne illness claim has two halves. Product liability answers the person who got ill. The cost of closing, deep cleaning, disposing of stock and reopening is a food contamination endorsement, and without it the operator funds the recovery themselves at exactly the moment revenue has stopped.
Every one of the three is an endorsement rather than a policy, which makes them inexpensive to add and easy to leave off a schedule that otherwise looks complete. Our brokers read all three with you against how the kitchen actually runs, along with what your contract asks the policy to carry, which a landlord or an event venue will ask for before you set up.
Speak to our teamKitchen check
Each line below changes what a restaurant schedule has to carry. Nothing here is priced and nothing here is a quote.
What the schedule has to carry
Tick what applies and the cover it implies appears here.
Bring the hood inspection record and the equipment schedule. Between them they answer half of this list, and they are the two documents an underwriter asks for first.
Speak to our teamCost
Restaurant premiums vary more than almost any other commercial category, because a dry cafe and a late-night full-bar venue are not the same risk in any respect at all. Six inputs move it more than the rest.
The highest single driver. Dry operations pay materially less than full-bar venues, and the share of revenue coming from alcohol is what the liquor form is rated on.
Prior foodborne illness suits, slip-and-fall claims or liquor incidents significantly affect both carrier appetite and price, and appetite matters more here than in most classes.
Higher throughput means more customer exposure and more payroll, which drives both the liability and the workers compensation side.
Newer systems with documented inspection records lower property rates; older wiring and non-compliant hoods raise them. Documentation is doing as much work here as the equipment.
Urban markets and high-litigation states carry surcharges, and late-night operation is treated as a material risk factor across every line on the schedule.
Alcohol service and food handling protocols, in writing, reduce both workers compensation and liquor liability pricing. Undocumented training counts for nothing at underwriting.
Three marks is an input that moves a restaurant premium more than the others here. It is a relative weighting drawn from how carriers rate, not a rate and not a quote.
A standard $1 million general liability limit sounds substantial until it meets a multi-plaintiff food poisoning claim. Industry benchmarks for full-service restaurants and bar venues typically run $2M per occurrence and $4M aggregate, and some policies count defense costs inside the limit, where a six-figure defence drains a $1M policy before anybody settles. An umbrella adds a layer above the primary policies at a fraction of the cost of raising them.
Talk to an expertProcess
We understand your business first, then take it to the carriers who want to write it. An advisor walks you through the options and what they cost. No two files are the same, so what follows is the shape of a placement rather than a script.
What is cooked, what is held, what travels, and what share of revenue comes from alcohol. Those four answers decide which of the food endorsements you need and which markets will look at the file at all.
Hospitality and liquor risk is a class standard carriers have been narrowing appetite on, so the file goes to the markets that genuinely write it rather than to whoever quoted last year. An advisor explains where the forms differ.
A sub-limited assault and battery provision, a food contamination exclusion, or a spoilage limit sized to nothing in particular. We read for those with you before you sign rather than after, and handle how COIs get issued for the landlords and event venues that want one before you set up.
Not one policy. General liability, commercial property and workers compensation as the base, with liquor liability, food contamination, spoilage and business income added according to what the kitchen actually does.
Usually not in full. The property form excludes breakdown and power failure; the stock needs a spoilage endorsement sized to your cold storage rather than to your turnover.
Product liability responds to the claimant. The cost of closing, deep cleaning, disposing of stock and reopening needs a food contamination endorsement, which is a separate thing and frequently missing.
Yes. The liquor exclusion on a standard general liability policy applies regardless of what you serve. If alcohol is a profit centre it needs its own cover.
Longer than most operators assume. A kitchen fire is usually a wait for equipment rather than for building work, and the standard twelve-month indemnity period is sized on the building.
Generally not. The landlord insures the structure and you insure the fit-out, the equipment and the stock, plus whatever the lease obliges you to carry on top.
A $1 million general liability limit is the floor and frequently not enough. Benchmarks for full-service and bar venues run $2M per occurrence and $4M aggregate, and on forms with defense inside the limit, defense costs erode them.
The premises risk is smaller and the food risk is identical. Product liability and contamination matter just as much, and a shared kitchen agreement adds a question about who is liable for what.
Get started
Whether you are placing cover for the first time or reviewing limits before a lease renewal, we submit across specialty and E&S markets that write hospitality properly, and we read the three food endorsements with you.
This page is general information, not a coverage determination. What your policy covers is governed by its own terms, conditions, and exclusions.