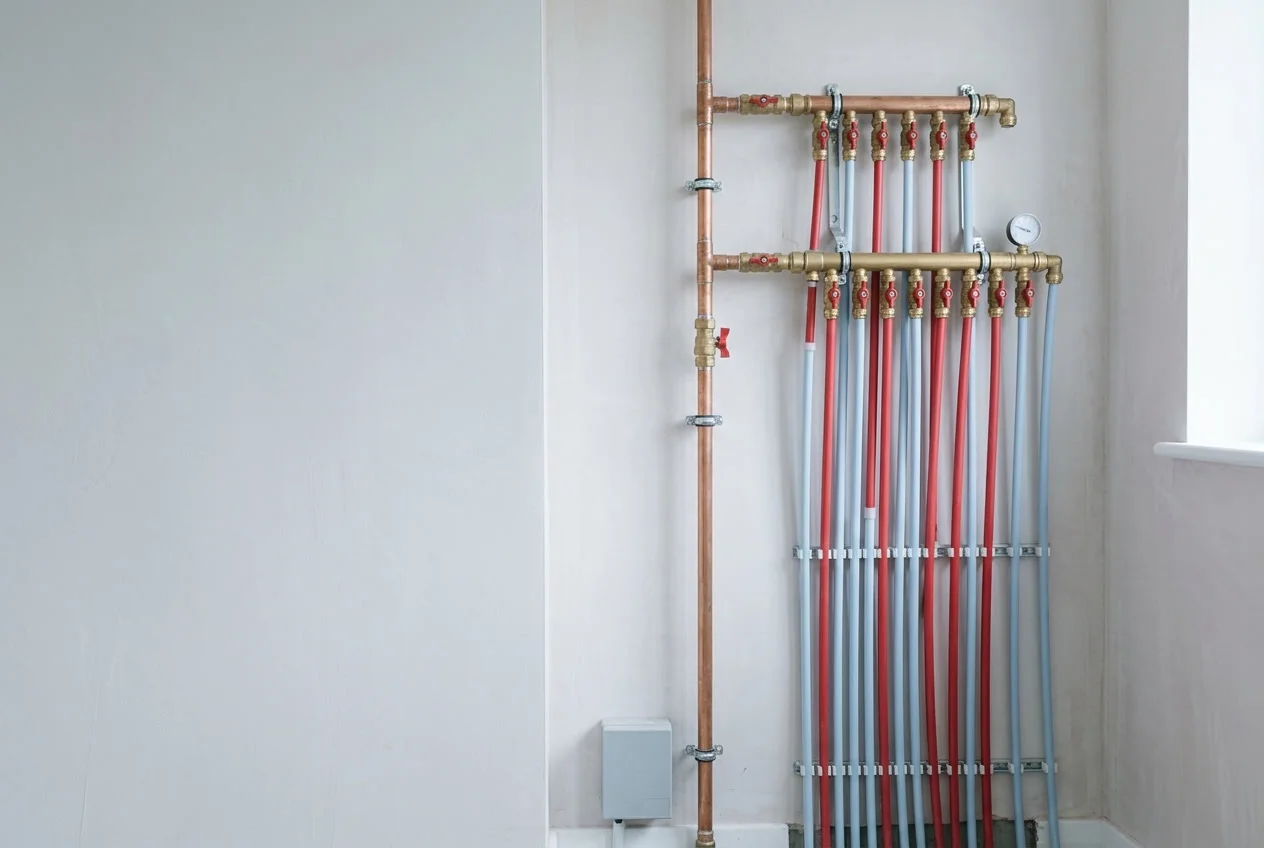
Copper supply lines and a pressure gauge on a plant room manifold

Plumbing insurance

Plumbing insurance usually combines general liability for water damage and third-party injury, workers compensation for employees, commercial auto for service vans, and tools and equipment cover. Many plumbing contracts and licence boards require proof of general liability before work can start.

Talk to an expert

Get a quote

Core coverage

What plumbing insurance covers

Two coverages carry the weight, and on a plumbing book the first one is doing more work than it does for almost any other trade.

01Carries the weight

General liability. The building around your work, once water gets into it.

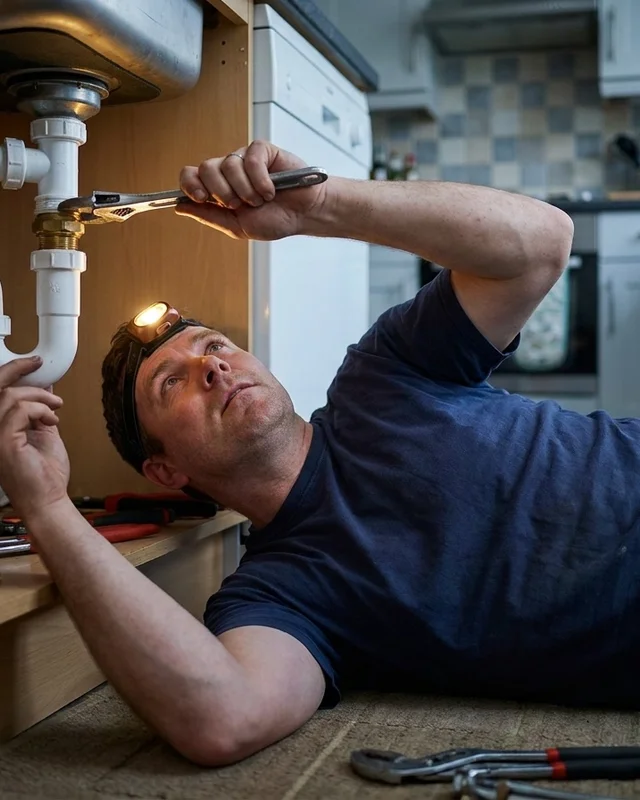
Third-party bodily injury and property damage arising from your work. A fitting that lets go behind a wall, a trap that overflows into the unit below, a customer who slips on a wet floor you left. On a plumbing book this is where the severity lives, because water travels.
02Carries the weight

Workers compensation. Your own crew.

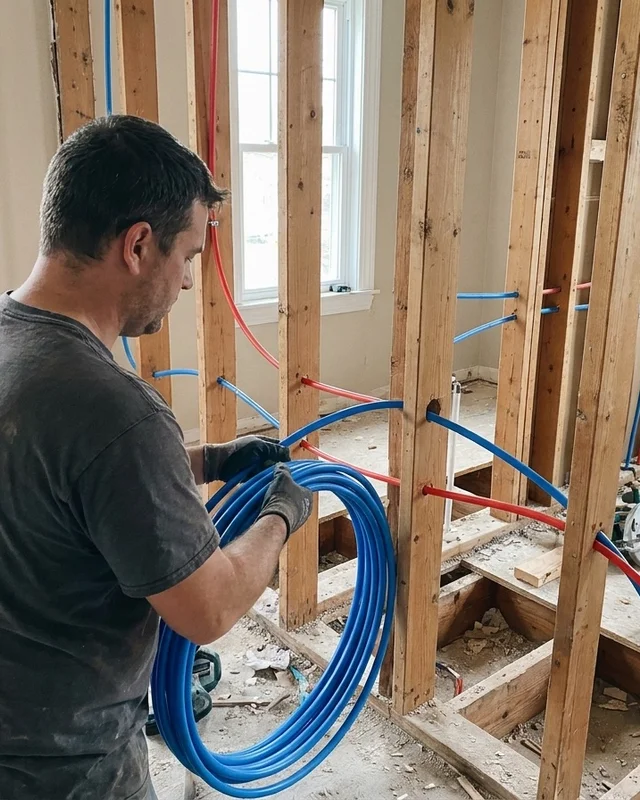
Medical costs and lost wages when a plumber is hurt on the job. The frequency sits with strains, cuts and burns from soldering; the severity sits with trench work and confined spaces. Your class code, not your safety record, sets the opening rate.

03Fills a gap

Contractor's equipment

Jetters, drain cameras, press tools, threading machines and locators. Written as inland marine, because a property policy covers little away from your premises and most of this lives in a van.

04Fills a gap

Commercial auto

Service vans, plus hired and non-owned auto for your own liability when an apprentice collects parts in a personal car. That second half is often missing from a schedule.

05Fills a gap

Contractor's pollution liability

The endorsement or separate policy that can put sewage, contaminated water and lead back into cover. For many plumbers this is not an optional extra, and the exclusions section explains why.

06Fills a gap

Care, custody and control

The water heater you removed, the fixtures stacked in the garage, the building you were left the keys to. General liability usually steps back once property is in your keeping.

07Fills a gap

Commercial property or a BOP

The shop, the yard, the fittings on the racks. Bundled into a business owner's policy for a smaller operation.

Equipment is the schedule that ages worst. A jetter and a camera can be a third of what is in the van, and neither tends to get added when it is bought. Our brokers can review jetters, cameras and press tools against a current inventory rather than last year's number, and against the rest of your construction cover where you run more than one trade.

Your operation

Four plumbing businesses, four different policies

Most plumbing companies run more than one of these, and the mix decides both the rate and which endorsements have to be on the schedule. Pick the closest match.

Residential service and repair

High call volume, small tickets, and your plumbers inside occupied homes every day. The exposure is rarely the fitting. It is the finished room the fitting sits above.

What underwriters askCall volume, number of plumbers, and how much of the work is inside occupied homes
The claim that shows upEscape of water into finished surfaces, a slip on a wet floor, damage to a customer's belongings
Endorsements it needsCare custody and control, pollution liability, hired and non-owned auto
Watch forA small leak found late can be a large claim. The repair is usually your cost; the ceiling, the cabinets and the floor below are usually the claim.Talk to a broker about this

If the share of sewer and drain work has grown since your last renewal, your policy may still be rated on the old mix. That is a conversation for before the anniversary.

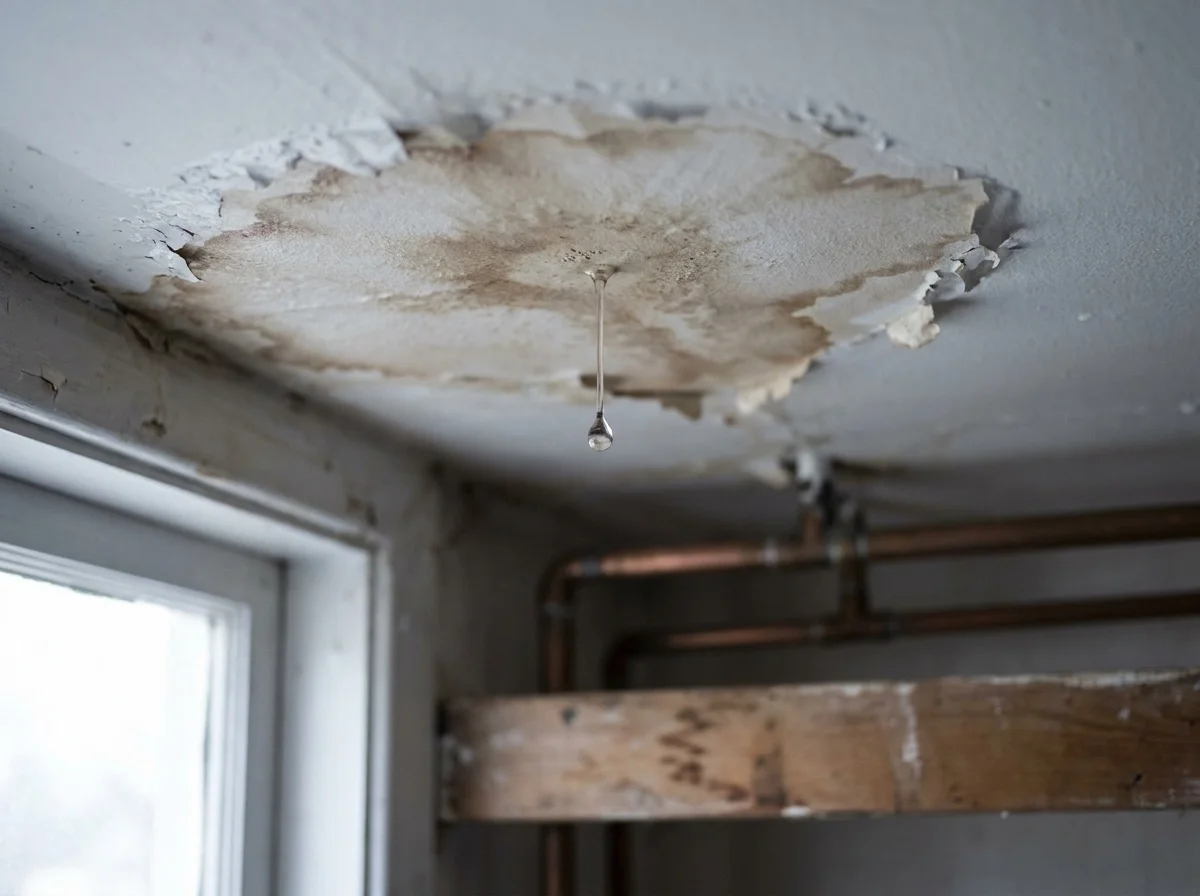
Water-stained, peeling ceiling with a drip falling above a run of copper pipe

Which water damage is actually yours

This is the part that decides plumbing claims. General liability generally pays for the damage your work causes to other property. It does not pay to put your own work right. Insurers call the second half the "that particular part" and "your work" exclusions, and it is the sentence most plumbers meet for the first time in a claim letter.

Where the line falls, in practice:

Typically not covered: The joint you soldered badly. Cutting it out and redoing it is generally your cost.

Typically covered: The ceiling, cabinets and flooring that joint soaked on its way down. Subject to your policy terms, that is third-party property damage.

Typically not covered: Re-running the repipe you routed wrong, because the pipework is the work itself.

Typically covered: Subject to your terms, the downstairs neighbour's apartment, once your line let go through their ceiling.

Timing decides the rest. A soldered joint that fails eighteen months later is not a job-site claim, it is a completed operations claim, and it usually draws on a products-completed operations aggregate kept separate from your general aggregate. On a busy service book that aggregate is the one that can quietly empty. Worth understanding claims that arrive after the job closed before you assume finished work is behind you.

The gaps

What plumbing insurance does not cover

Knowing these before a claim is considerably more useful than learning them during one. Eight that matter on a plumbing schedule.

Your own workmanship

WHAT YOU NEED

A standard policy will not fix this for your own crew's work. Resulting damage is generally covered, the rework is not, and damage arising out of a subcontractor's work is treated differently. Price rework into the job.

Sewage backup

WHAT YOU NEED

Contractor's pollution liability. A backup can be a water claim and a pollution claim at the same time, and where the pollution exclusion applies, only pollution cover responds.

Mould

WHAT YOU NEED

A mould buy-back where a carrier offers one. Mould follows water, and a common exclusion follows mould.

Backflow and cross-connection

WHAT YOU NEED

Pollution liability plus your testing records. Contaminating a potable supply can reach an entire building or beyond it.

Damage to that particular part

WHAT YOU NEED

Nothing, usually. This is the exclusion above stated in policy language, and it is the one worth reading in your own wording.

Employee injury

WHAT YOU NEED

Workers compensation. General liability answers for third parties, and your own crew is not a third party.

Anything involving a vehicle

WHAT YOU NEED

Commercial auto, plus hired and non-owned. General liability stops at the van door.

Underground utility strikes

WHAT YOU NEED

An exclusion buy-back if you dig at all. Many contractor policies exclude damage to underground services unless it is bought back.

Sewage, mould and backflow are the three that separate a plumbing placement from a general contractor's, and two of the three route back to the same pollution exclusion. Every one of them is easier to address at quote stage. Speak to our team about which of them your work actually reaches, and about cover for an injured crew member if you are carrying staff.

Lead service lines

What the lead service line rule changed

The EPA's Lead and Copper Rule Improvements put a national deadline on work that can land on licensed plumbers. Three things changed, and only one of them is about pipe.

Water-stained, peeling ceiling with a drip falling above a run of copper pipe

There is now a date

The EPA finalised the Lead and Copper Rule Improvements in October 2024, effective 30 December 2024. Water systems have to publish a service line replacement plan by 1 November 2027, and for most systems a ten-year replacement programme starts from there. A water industry challenge to the rule is still before a federal court.

Copper supply lines and a pressure gauge on a plant room manifold

The work arrives at your door

Replacement volume at that scale is likely to be carried out largely by contractors, licensed plumbers among them, much of it in older housing stock. If your revenue mix shifts toward service line work, the policy that was rated on service and repair may no longer describe the business.

Exposed pipework rising through the service riser of a commercial building

Lead often counts as a pollutant

That matters more than the plumbing does. A lead exposure claim can be treated as a pollution claim, and many wordings also exclude lead by name, so the exclusion that catches sewage can catch this too. Confirm in writing what your wording says about lead disturbance before you take the work, not after.

None of this changes what general liability does. It changes which endorsements have to be on the schedule and which carriers will write you once lead work is a real share of your revenue. Requirements also sit on top of what your state licence board expects.

Speak to our team

Scope check

Which of these does your crew do?

A standard contractor wording assumes dry work. Nearly every line below is a reason a plumbing file needs something added to it. Nothing here is priced and nothing is submitted.

Gaps this opens in a standard wording

Nothing ticked yet. Choose the work your crew actually does and the gaps will list here.

Print this before your renewal meeting. Several of these are a single endorsement, and all of them are easier to settle at quote stage than to argue at claim stage. This is general information about how these coverages usually work, not a determination about your policy: what responds depends on your wording and your carrier.

Speak to our team

Cost

How much does plumbing insurance cost?

There is no flat answer, and a number quoted without seeing the operation is a guess wearing a price tag. Six inputs move a plumbing premium more than the rest.

01

Payroll and workers comp class code

The largest single driver. Plumbing carries its own class code, distinct from HVAC and from sheet metal, and a business running both trades under one code may be paying on the wrong one.

Effect on premium
02

How much sewer and drain work you do

The share that involves sewage can move the liability appetite more than almost any other answer, because it can move the claim from water into pollution.

Effect on premium
03

Your revenue split

New construction rates differently from service and repair. Carriers ask for the percentage, and they check it at audit.

Effect on premium
04

Vehicles and radius

Van count, radius, and what stays in the van overnight. On a wet trade the contents can be worth more than the vehicle, and the two are rated separately.

Effect on premium
05

Claims history and experience modifier

Three years of loss runs and the modifier that falls out of them. On a trade where one escape of water can be six figures, a clean history is worth more here than almost anywhere.

Effect on premium
06

Limits and required endorsements

The pollution endorsement, the equipment schedule, the additional insured and waiver wording your builders demand. Each one is priced.

Effect on premium

Three marks is an input that moves a plumbing premium more than the others listed here. It is a relative weighting drawn from how these behave on a wet trade, not a rate and not a quote.

So what does that add up to?

Your comp premium is largely settled by payroll and class code before an underwriter looks at you. Your liability premium is where the shape of the business shows through, and on a plumbing book the sewer share can move it further than almost anything else. Request a quote and we will take your real exposure to market.

Talk to an expert

Process

How a placement works

We understand your business first, then take it to the carriers who want to write it. An advisor walks you through what comes back and what it costs. No two files are the same, so what follows is the shape of a placement rather than a script.

  1. Loss runs and a payroll schedule spread on a desk beside a calculator and laptop

    We understand the business first

    What you do, where, with how many people, and what your contracts oblige you to carry. Those answers decide which markets will look at the file at all, and how much of the rest of this applies to you.

  2. Brokerage desk with a monitor in morning light

    We match it to the carriers who want to write it

    One set of information goes to underwriters we know have appetite for plumbing work rather than whoever happened to quote last renewal. An advisor talks you through what comes back and what it costs.

  3. Stamped certificate on a clipboard with a pen and a magnifier

    After bind, certificate requests read against the contract

    A main contractor wants proof before your crew can start, and this is how COIs get issued here. We read the certificate request against your contract, so the endorsements the contract needs are requested on the policy and the certificate reports what the policy provides, rather than a generic endorsement that may fail review.

In practice, yes, though not by federal statute. Most states licence plumbing at state level and the rest leave it to the city or county, and many licensing authorities ask for proof of general liability before they will issue or renew a licence. Builders ask second. Workers compensation follows its own rule: required in every state except Texas and South Dakota, where it is optional, with the employee count that triggers it set state by state. In Texas it is elective for private employers but still required on public building and construction contracts.

The honest answer is that the sewer percentage can move the liability side further than almost anything else, and no one can price a plumbing file without knowing it. Payroll, class code, vehicle count and loss history do the rest. We would rather ask six questions than publish a starting-from figure that turns out to describe nobody.

It typically covers the damage the water does to other property, subject to your policy terms. It does not cover putting your own work right. If a joint you soldered fails and soaks a ceiling, the ceiling is generally the claim and the joint is your cost. That split is the single most useful thing to understand about a plumbing policy.

Often not without pollution cover. A backup can be a water claim and a pollution claim at once, and the pollution exclusion on many contractor general liability policies can reach sewage. Contractor's pollution liability is the usual way to put it back in cover. Any contractor doing sewer or drain work should confirm this specifically.

Many general liability policies exclude mould by endorsement, and mould follows water, so a plumbing claim can turn into an uncovered one some weeks after the leak. Some carriers offer a limited buy-back. Whether yours does is worth knowing before you need it rather than after.

Generally not. General liability responds to damage your work causes to other property, not to the cost of correcting the work itself. Insurers express this through the "that particular part" and "your work" exclusions. Contractors errors and omissions can narrow the gap in some cases, but nothing closes it completely.

Possibly not, and the exemption is real in most states for a sole proprietor. It is also a commonly regretted saving on this trade. Builders tend to require comp whatever your state says, and the first time you put an uninsured helper on a job you may have quietly taken on their injuries too.

Commonly $1M per occurrence and $2M aggregate on general liability, often with an umbrella layer on larger commercial work, plus additional insured status, waiver of subrogation and primary and non-contributory wording. Read the contract rather than the certificate request, because the two do not always agree.

Get started

Get a plumbing policy that expects water.

Tell us what you work on and where. We will go to market for terms that address escape of water, sewage and the damage from a joint you soldered eighteen months ago.

  • Contract insurance schedules read with you
  • Direct and wholesale carrier access
  • Markets that write plumbing work

This page is general information, not a coverage determination. What your policy covers is governed by its own terms, conditions, and exclusions.

Exposed pipework rising through the service riser of a commercial building