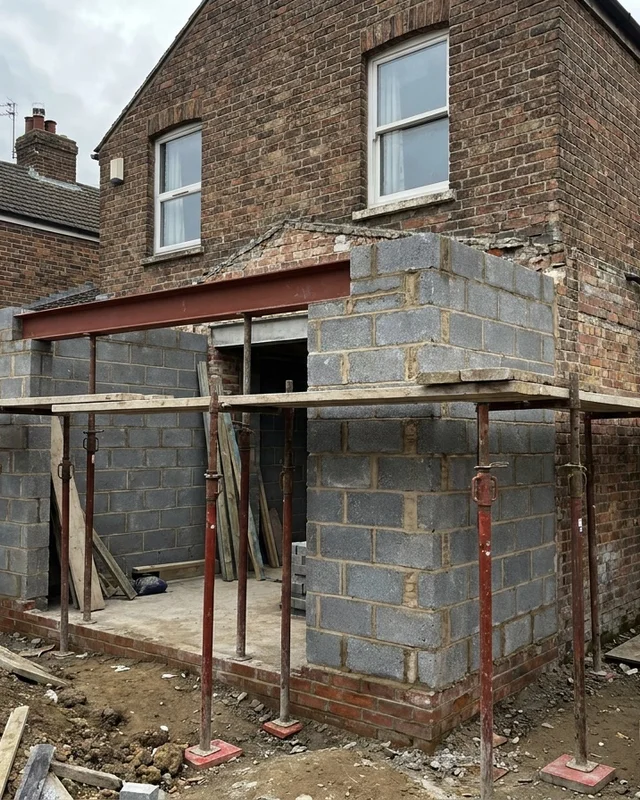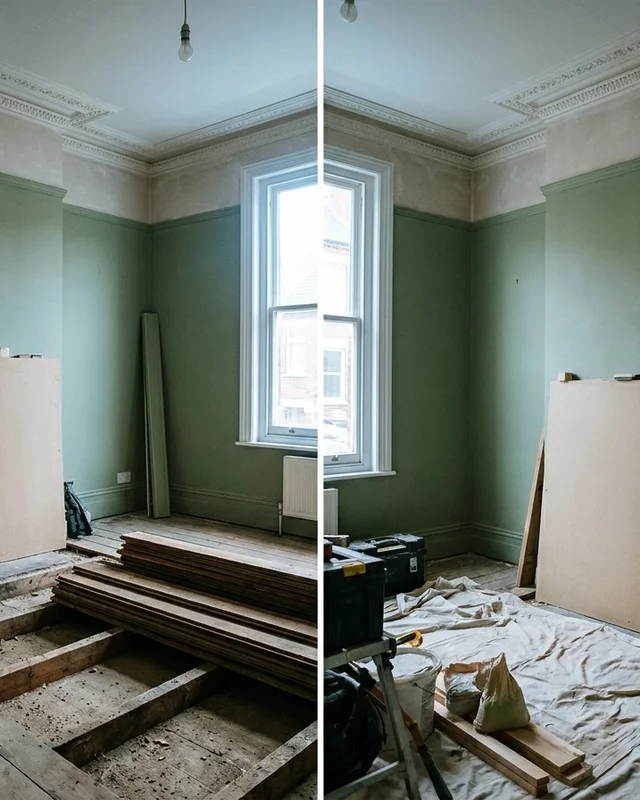
Residential room part way through renovation with dust sheets and a folded step ladder

Remodeler insurance

Remodeler insurance typically combines general liability for damage to an occupied home, workers compensation, tools and equipment, and installation floater cover for materials in transit. Working inside a client's existing structure is what separates it from new-build cover.

Talk to an expert

Get a quote

Core coverage

What remodeler insurance covers

Two lines carry a remodel, and the first one is doing something it never has to do on a new build: answer for a building that was already there.

01Carries the weight

General liability. The house around your work, and the people living in it.

Third-party injury and property damage arising from your work. Damage to finished rooms you were not working in, a client hurt moving through a live site, dust and debris reaching parts of the home nobody agreed to open up. On a remodel the building itself is the third party.
02Carries the weight

Workers compensation. A crew working inside a finished building.

Medical costs and lost wages when someone on your crew is hurt. Remodeling injuries cluster around demolition, stairs, awkward access and the hazards of a structure nobody has a drawing for. Your class code sets the opening rate before anything else is discussed.

03Fills a gap

Care, custody and control

The kitchen you took out and stored, the furniture you moved, the appliances stacked in the garage. On a remodel you are constantly holding property that belongs to the client.

04Fills a gap

Installation floater

Materials in transit and on site before they are fitted. Cabinetry, stone, glazing and fixtures sitting in a hallway are often outside your own policies until somebody writes a floater.

05Fills a gap

Tools and equipment

Written as inland marine. On a remodel the site is somebody's home rather than a secured compound, and the security assumptions in the wording are worth reading.

06Fills a gap

Contractors errors and omissions

Where you design as well as build. Drawing the layout, specifying the beam or advising on the spec is professional advice, and contractor GL policies normally carry an endorsement excluding it.

07Fills a gap

Subcontractor controls

Not a policy, a process. Most remodels involve trades you do not employ, and their insurance, evidenced by a certificate, is what helps stop their failures becoming your claims.

The installation floater is a line often missing entirely, because materials feel like somebody else's problem right up until a delivery of cabinetry is stolen from a hallway. Our brokers can review it alongside what the tool schedule actually lists and against the construction program above this one where remodeling is only part of what you do.

Your projects

Four remodels, four different policies

Many remodelers take on several of these, and it is often the heaviest one you accept rather than the typical one that decides how the file is rated. Pick where your largest projects sit.

Kitchen remodels

The highest-value room in the house, with water, gas, electricity and expensive finishes arriving in the same six weeks. Also the room a family cannot do without, which shapes every conversation about delay.

What underwriters askProject values, how much you self-perform, and whether the household stays in residence
The claim that shows upWater damage after a connection, damage to stone or cabinetry in storage, delay claims from the client
Endorsements it needsInstallation floater, care custody and control, subcontractor certificate process
Watch forStone and cabinetry usually arrive weeks before they are fitted. Between delivery and installation they can fall outside your policies unless a floater says otherwise.Talk to a broker about this

If you have started opening structure or taking on pre-war stock, the policy written for kitchens and baths no longer describes the risk you are carrying.

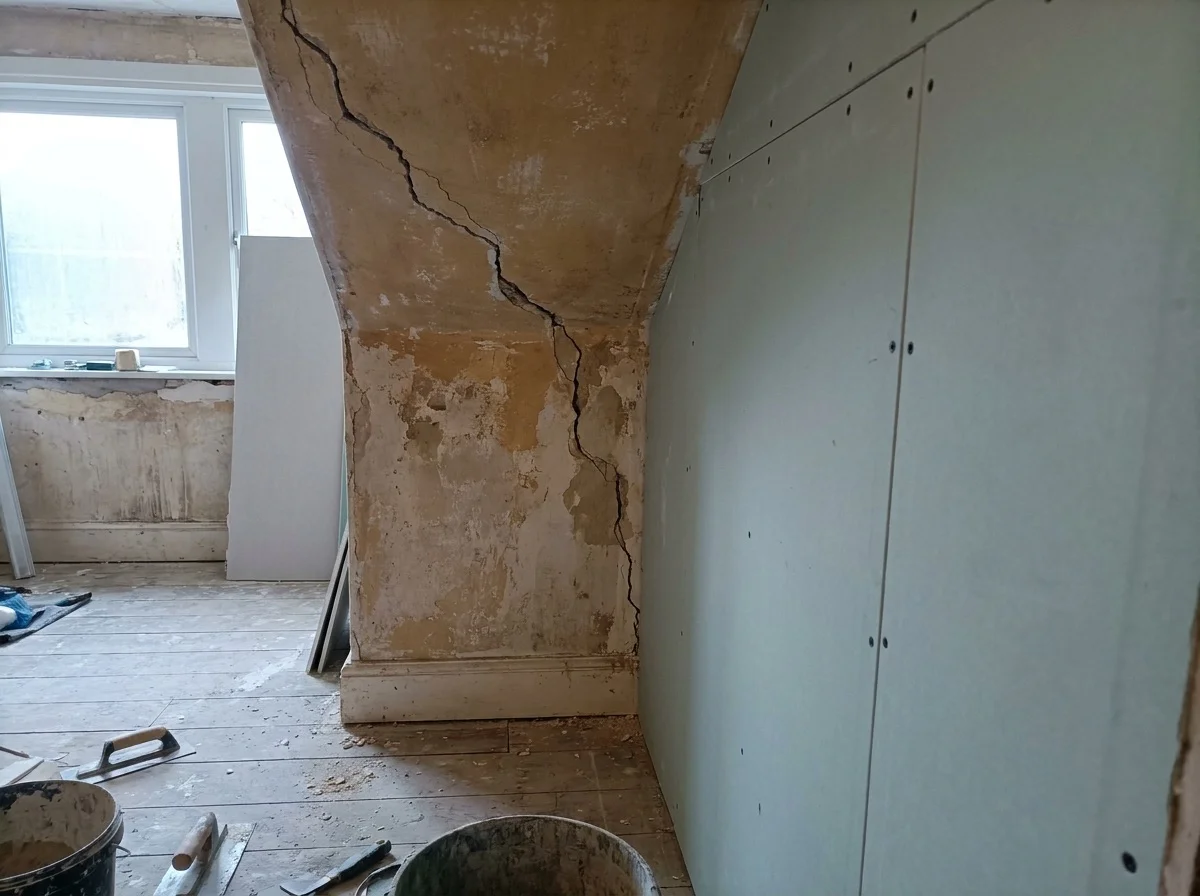
Crack running through original plaster beside a section of new plasterboard

Who owns what was already wrong

This is the argument that defines remodeling insurance. General liability answers for damage your work causes to other property. On a remodel, the other property is a house that was already there, already ageing, and already carrying whatever the last four owners did to it. Separating your damage from its condition is the whole game.

Where the line tends to fall:

Typically covered: A wall you demolished bringing down finishes in the room next door. Subject to your terms, that is damage your work caused to other property.

Typically not covered: Redoing the part of the remodel you got wrong. The rework is generally your cost on this trade, as it is on every other.

Typically covered: Water reaching the floor below after a connection you made failed during the works. Mould that follows is often excluded by endorsement.

Typically not covered: A defect that was in the house before you arrived, which the client noticed once you were on site. Pre-existing condition is not your claim, but it can become your argument.

Which is why the most valuable thing a remodeler does on day one costs nothing: photograph everything before you touch it. A dated record of the existing condition is the difference between a conversation and a claim, and it is often the only evidence that will ever exist. It can matter more than any endorsement on the schedule, and it is worth reading alongside how cover behaves once a job is closed, because that is where the late arguments land.

The gaps

What remodeler insurance does not cover

Eight that matter on a remodeling schedule. Most of them exist because you are working inside a building somebody else built.

Your own workmanship

WHAT YOU NEED

A standard policy will not fix this for your own crew's work. Resulting damage is generally covered, putting your own work right is not, and damage arising out of a subcontractor's work is treated differently. Price the snag list into the contract.

Pre-existing defects

WHAT YOU NEED

A photographic record made before you started. Not a policy at all, and often more useful than one.

Lead, asbestos and mould

WHAT YOU NEED

Contractors pollution liability, checked for what it includes. Older stock can contain all three, and contractor GL wordings commonly exclude all three, through the pollution exclusion or by endorsement.

Weather through an open structure

WHAT YOU NEED

Builders risk or an equivalent, arranged before the roof comes off. General liability answers for weather damage only where your work caused it, and not for the works themselves.

Design and specification

WHAT YOU NEED

Contractors errors and omissions. Drawing the layout or specifying the beam is advice, and contractor GL policies normally carry an endorsement excluding it.

Employee injury

WHAT YOU NEED

Workers compensation. General liability answers for third parties, and your crew is not a third party.

An uninsured subcontractor

WHAT YOU NEED

Certificates collected before anyone starts. Some wordings restrict cover for work done by a sub who cannot produce one.

Delay and consequential loss

WHAT YOU NEED

Rarely anything. A client's hotel bill because the kitchen ran over is generally a contractual argument, not an insured one. Manage it in the contract.

The second card is the one worth acting on today, because it costs nothing and it is the only one you can still fix on a job that has already started. Speak to our team about the pollution position before you take on older stock, and about cover once the crew grows if you are hiring for the season.

Older stock

What you find when you open the wall

Remodeling is one of the few trades whose risk is largely invisible at quoting stage. Three things hide inside older buildings, and each one can change the policy rather than just the programme.

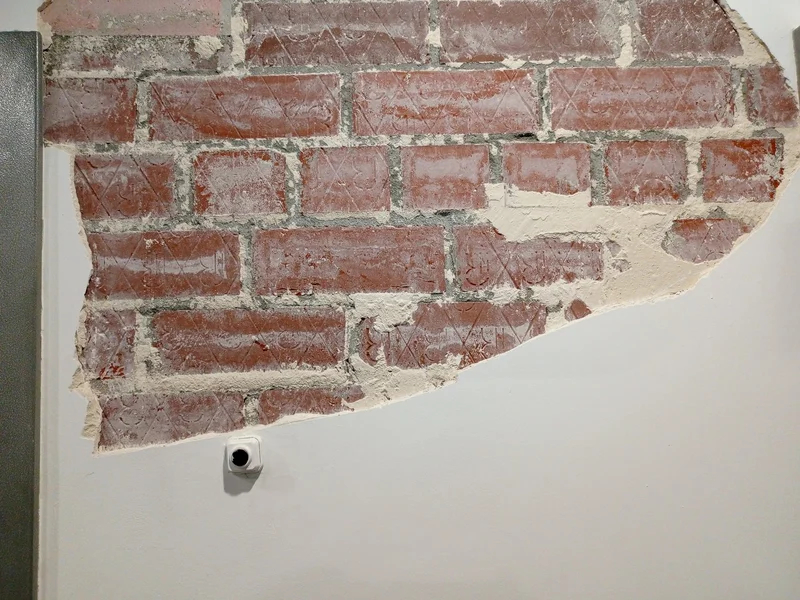
Old brickwork exposed where plaster has come away from an interior wall

Materials that were legal at the time

Lead paint and asbestos were ordinary building products for decades, and both are still sitting in a great deal of housing stock. Disturbing either turns a remodel into a pollution event, and the pollution exclusion, with the lead and asbestos exclusions many contractor wordings add, means a plain general liability policy often will not answer for it.

Cables and chased channels revealed in the stripped wall of an older apartment

Work nobody documented

Undocumented alterations by previous owners are the norm rather than the exception. A wall that turns out to be load bearing, a circuit that runs somewhere unexpected, a beam that was never sized. You inherit the consequences of decisions you were never told about.

Water staining spreading across a ceiling below a failed roof

A building that is now open to weather

Once a roof or an external wall is opened, the whole house is exposed and that exposure is on your watch. General liability answers only where your work caused the damage, so the cover written for weather is builders risk or its equivalent, with the existing structure confirmed, and it has to be in place before the opening rather than after the forecast changes.

None of this is avoidable on older stock, and all of it is manageable. Test before you disturb, document what you find, and confirm your pollution position before you price the job rather than after you open the wall. It sits alongside the EPA lead renovation rule for homes built before 1978 and whatever your state requires of a licensed contractor, which govern who is permitted to do the work at all.

Speak to our team

Project check

What do your projects actually involve?

A remodeling policy is often rated on the heaviest work you accept, not the average job. Most lines below change the wording or the limits. Nothing here is priced and nothing is submitted.

What the schedule needs to answer for

Nothing ticked. Choose what your projects involve and the cover it implies will build here.

Bring this to your renewal. On this trade three protections do a lot of the work, a floater, a pollution endorsement and a camera, and all three are easier to arrange before a job than during one. This is general information about how these coverages usually work, not a determination about your policy: what responds depends on your wording and your carrier.

Speak to our team

Cost

How much does remodeler insurance cost?

No flat figure survives contact with a real project list. Six inputs move a remodeling premium further than the rest.

01

Whether you touch structure

The single biggest divider on this trade. Kitchens and baths are one risk; opening load-bearing walls and adding footings is another, and carriers often price them as different businesses.

Effect on premium
02

Payroll and class code

Comp is built on payroll, and remodeling classes often sit above finishing trades because demolition and awkward access produce real injuries.

Effect on premium
03

The age of the stock you work on

Older housing brings lead and asbestos, and the pollution position that follows. It is worth settling before a job, and an expensive thing to discover missing.

Effect on premium
04

Whether you design

Design-build brings a professional exposure that a pure build contractor does not carry, and it needs its own cover rather than a bigger liability limit.

Effect on premium
05

How much you subcontract

Uninsured subcontractor payroll is often charged as yours at audit, so the certificate process is a premium question as well as a claims one.

Effect on premium
06

Claims history and project values

Three years of loss runs alongside your typical and largest contract. On this trade a single water claim in an occupied home can outweigh several clean years.

Effect on premium

Three marks is an input that moves a remodeling premium more than the others listed here. It is a relative weighting drawn from how these behave on existing-structure work, not a rate and not a quote.

So what does that add up to?

The line that matters is structural. A remodeler who stays inside finishes is often priced close to a fit-out trade; one who opens walls, close to a builder. Most businesses sit somewhere between and are often rated as whichever they described last. Request a quote and we will take your real exposure to market.

Talk to an expert

Process

How a placement works

We understand your business first, then take it to the carriers who want to write it. An advisor walks you through what comes back and what it costs. No two files are the same, so what follows is the shape of a placement rather than a script.

  1. Loss runs and a payroll schedule spread on a desk beside a calculator and laptop

    We understand the business first

    What you do, where, with how many people, and what your contracts oblige you to carry. Those answers decide which markets will look at the file at all, and how much of the rest of this applies to you.

  2. Brokerage desk with a monitor in morning light

    We match it to the carriers who want to write it

    One set of information goes to underwriters we know have appetite for remodeling work rather than whoever happened to quote last renewal. An advisor talks you through what comes back and what it costs.

  3. Stamped certificate on a clipboard with a pen and a magnifier

    After bind, certificate requests read against the contract

    A client, a condo board or a main contractor wants proof before your crew can start, and this is how COIs get issued here. We read the certificate request against your contract, so the endorsements the contract needs are requested on the policy and the certificate reports what the policy provides, rather than a generic endorsement that may fail review.

The existing structure. A builder starts from nothing and is responsible for what they create; a remodeler works inside a building that already exists and takes on responsibility for the parts they touch, next to parts they do not. That difference drives the cover: builders risk, care custody and control, and pollution for older materials all behave differently on a remodel.

Potentially, if your work caused it. General liability responds to damage your operations cause to other property, and on a remodel the rest of the house is other property. What it generally will not do is pay for a defect that was already there, which is why a dated photographic record before you start can be worth more than most endorsements.

If you open the structure or the weather envelope, generally yes. Once a roof or an external wall is off, the whole building is exposed, and general liability answers for rain or wind only where your work caused the damage, not for the works themselves. A renovation builders risk form does not always include the existing structure, so confirm it. It needs to be arranged before the opening rather than once a forecast changes.

It is usually treated as a pollution claim rather than a property one, and contractor GL wordings commonly exclude pollution, lead and asbestos. Contractor's pollution liability is what can put it back inside your cover, subject to its own terms. On homes built before 1978 the EPA lead renovation rule also generally requires a certified firm and lead-safe work practices, and testing before demolition is what keeps the conversation short.

Usually only with an installation floater or builders risk. Cabinetry, stone, glazing and fixtures delivered ahead of the fit sit in a gap: often no longer the supplier's, not yet part of the client's home, and not part of your tools. A floater is written to close that gap, subject to its terms.

Generally not. A client's costs from an overrun are a contractual matter rather than an insured one, and liability policies generally do not respond to pure economic loss. The place to manage it is the contract, with realistic dates and a clear variation process.

Usually yes. Drawing the layout, sizing a beam or specifying materials is professional advice, and contractor general liability policies normally exclude professional advice by endorsement, regardless of how good the build is. Contractors errors and omissions is what covers the design half of a design-build business.

Not as their insurance, and often less than people assume. Some wordings restrict or remove cover for work performed by a subcontractor who cannot produce a valid certificate, and uninsured subcontractor payroll is often charged as yours at audit. Collect certificates before anyone starts.

Get started

Cover for the house you did not build.

Tell us how much structure you open and how old the buildings are, and we will go to market for terms that account for what is already inside the walls.

  • Contract insurance schedules read with you
  • Direct and wholesale carrier access
  • Markets that write remodeling work

This page is general information, not a coverage determination. What your policy covers is governed by its own terms, conditions, and exclusions.

Older brick house wrapped in scaffolding with protective sheeting over the roof